 is your investment to the Victory and future of Ukraine


14.09.2026
The reconstruction of housing, the energy sector, transportation, and urban infrastructure requires long-term funding — and budgets and grants alone will not be enough. Municipal bonds could serve as an additional source of funding for communities.
Today, this instrument is virtually non-existent in Ukraine: over the past three decades, only 19 cities have issued bonds, and the most recent issuance took place in 2021. The Commission has already simplified the rules for issuing them, and the next task is to create conditions under which local communities can actually enter the market with well-prepared projects, and investors can understand the terms, returns, and risks of such investments.
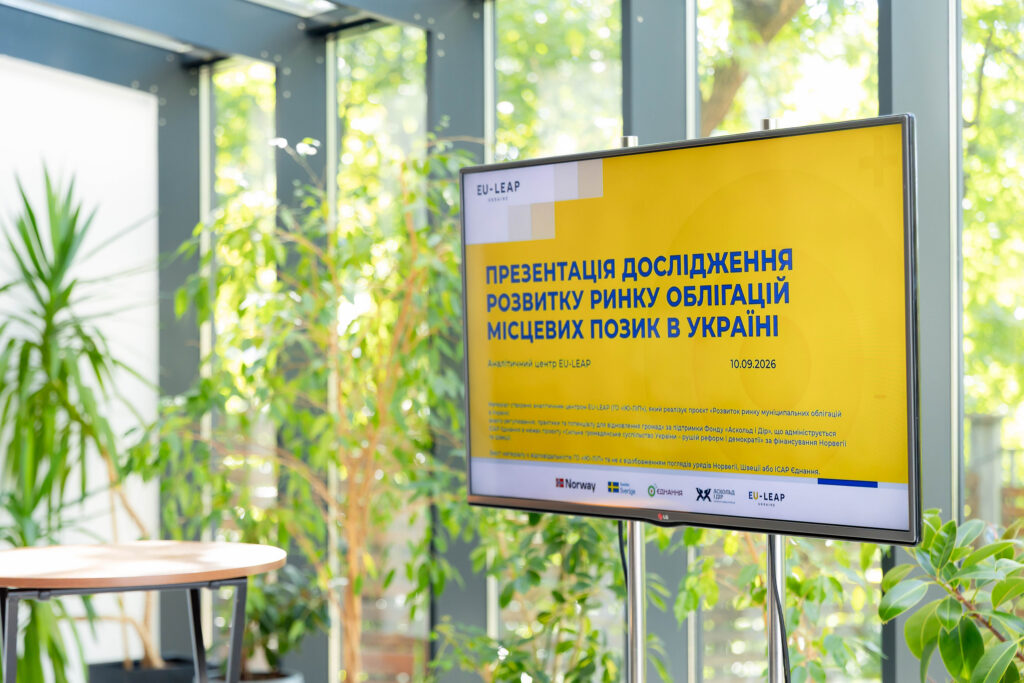
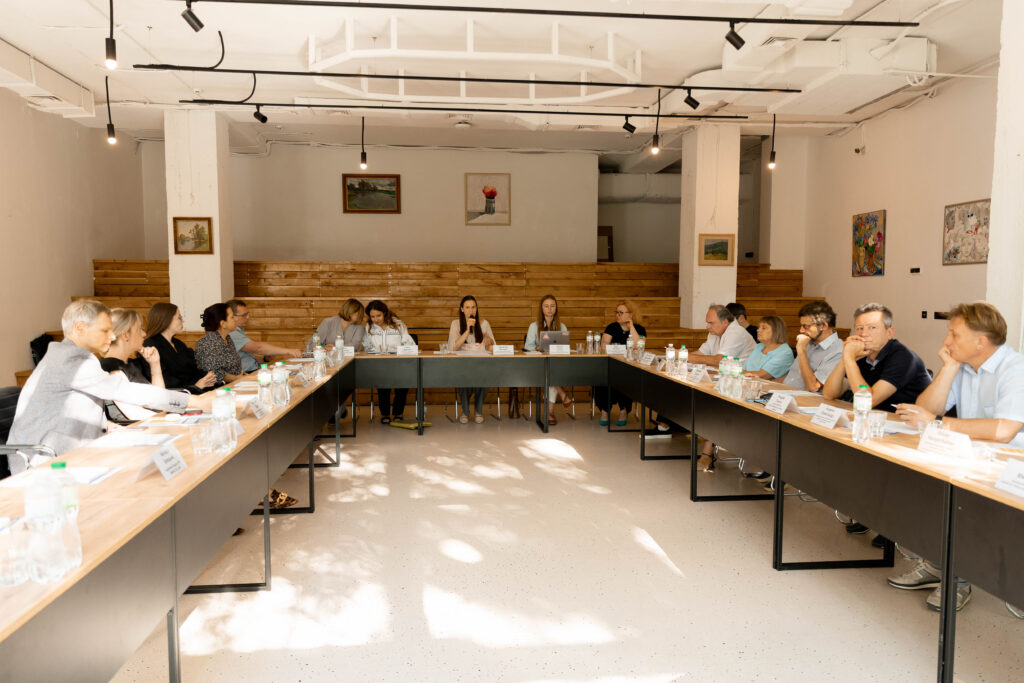
Representatives of the NSSMC discussed these issues during a presentation of a study by the EU-LEAP Analytical Center on the development of the local bond market in Ukraine.
The mechanism is quite simple: a community has a specific project — for example, the modernization of heating networks, the construction of an energy facility, or the restoration of social infrastructure. To implement it, the city can issue bonds and raise funds from investors. The investor, in turn, receives a security with a specified maturity date and terms for income payments.
At the same time, bonds are not free money. They represent a debt that the community must repay. Therefore, entering the market should not begin with the desire to simply raise funds, but rather with a high-quality project, a realistic financial model, and a clear understanding of the sources from which the city will service its obligations. It is the community’s financial capacity, a well-prepared investment project, and responsible risk management that are the fundamental prerequisites for utilizing this tool.
The Commission already simplified the procedure
In 2026, the NSSMC updated the rules for issuing local government bonds.
In particular, the Commission eliminated the link between the issuance volume and the development budget deficit, allowed the use of a base prospectus, introduced electronic submission of documents, and shortened the review periods.
At the same time, barriers still exist in the market. Among them, the panelists cited complex and lengthy procedures, duplication of information among government agencies, tax asymmetry between municipal bonds and government bonds, limited opportunities for foreign investors, and insufficient institutional support for communities preparing to enter the capital market.
A separate potential — green bonds
For Ukrainian communities, this tool may be particularly relevant in the context of energy sector recovery, energy efficiency, and increasing energy independence.
Through green bonds, communities can raise funds for projects that have a measurable environmental impact: the modernization of heating networks, energy efficiency in buildings, renewable energy, clean transportation, and other “green” infrastructure.
But the term “green bond” alone is not enough. Investors need to understand exactly which project their funds are going toward and what environmental impact it will have.
That is precisely why the development of this segment requires a clear procedure for confirming environmental benefits, as well as independent assessment and verification of projects. Representatives of the Commission specifically emphasized this point during the discussion.
The next step: the first practical issues
The participants agreed that preparations for pilot issuances should begin immediately, while simultaneously improving legislation and market infrastructure.
The first projects to be implemented may be relatively small, well-prepared initiatives whose results residents and investors will be able to see firsthand in their own community. Successful projects will provide practical models that can later be replicated and scaled up in other cities.
Representatives of the Verkhovna Rada of Ukraine, the NSSMC, the National Bank of Ukraine, the World Bank, local self-government bodies, international organizations, and professional associations took part in the discussion.
The event took place as part of the EU-LEAP Analytical Center’s project “Development of the Municipal Bond Market in Ukraine: An Analysis of Regulation, Practices, and Potential for Community Recovery.”
The project is being implemented with the support of the Askold and Dir Foundation, which is administered by ISAR Yednannia as part of the project “A Strong Civil Society in Ukraine — A Driving Force for Reform and Democracy,” funded by Norway and Sweden.
The content of this research is the sole responsibility of the EU-LEAP Analytical Center and does not reflect the views of the governments of Norway, Sweden, or ISAR Yednannia.
Зв'язатися з нами